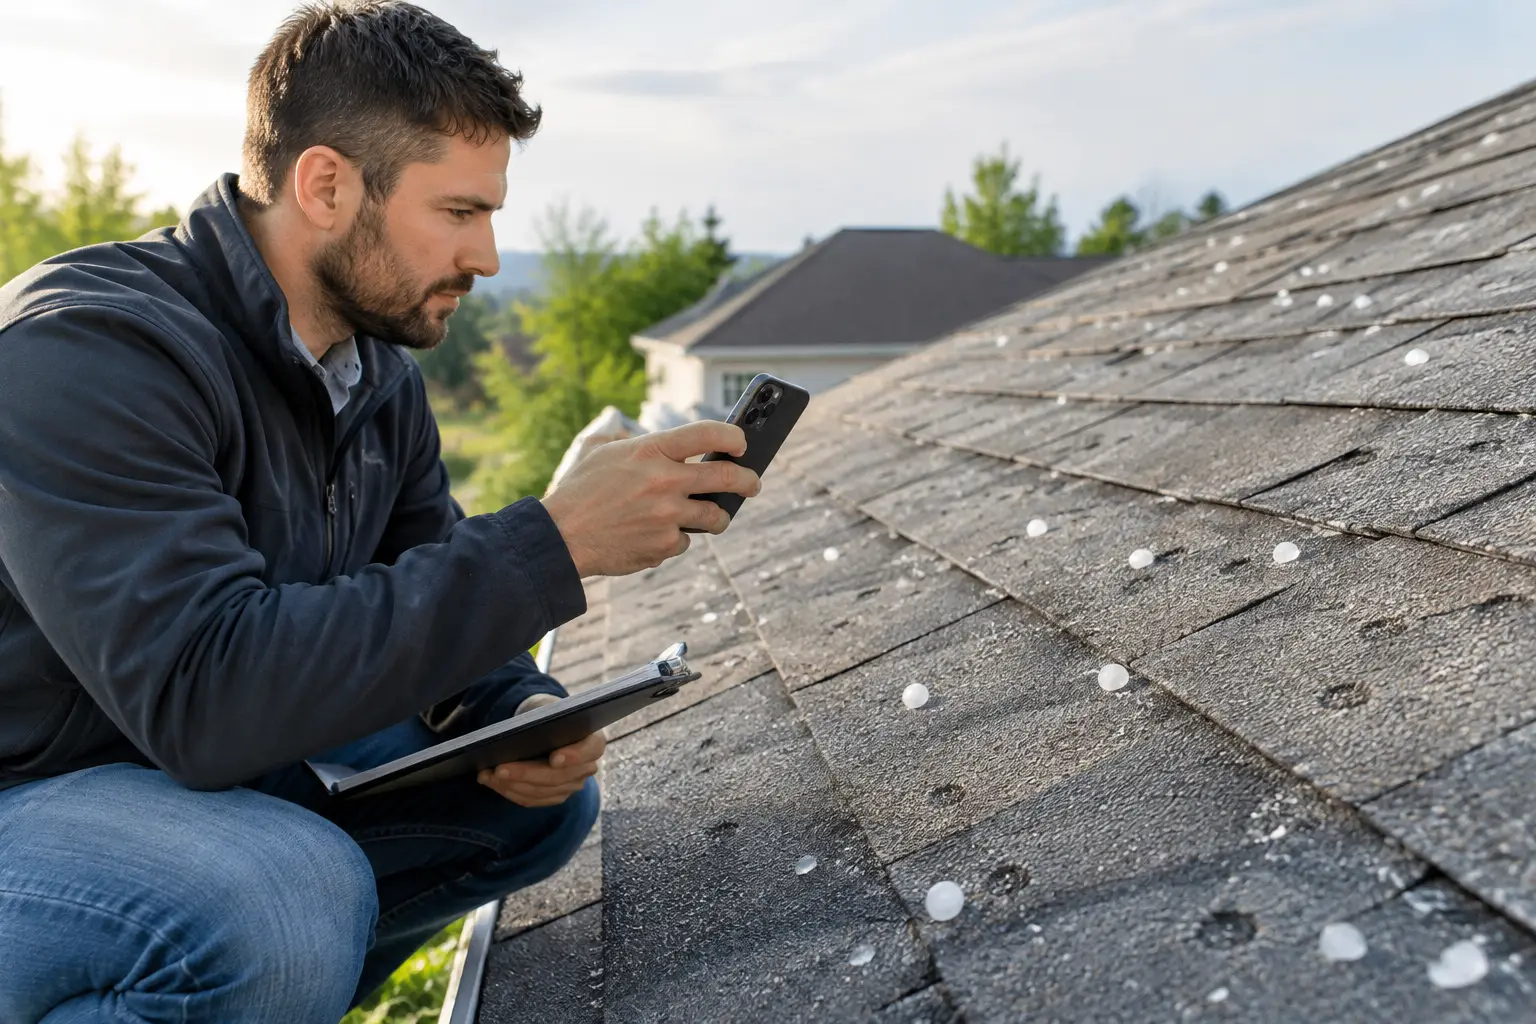
A hailstorm can leave a roof looking normal from the driveway while bruising shingles, loosening granules, denting metal, and damaging soft-metal components above it. That gap between what is visible from the ground and what an insurer can verify is why roof hail damage insurance documentation matters. The goal is not to build a dramatic story. It is to create an accurate record of the roof’s condition, the storm event, and the work needed to restore the system.
For Baytown and greater East Texas property owners, a well-documented claim starts with facts: dated photos, a safe on-roof inspection, maintenance history, weather information, and a written scope that explains what was found. Good documentation can support a claim. It does not guarantee coverage, because policy language, deductibles, prior damage, and the insurer’s findings all matter. But it gives you a much clearer basis for the conversation.
Start documenting before temporary repairs hide the evidence
After a hail event, protect the building first. If water is entering the home or commercial space, use reasonable temporary measures such as a tarp or emergency leak repair. Keep receipts, take photos before and after the temporary work, and avoid making permanent repairs to suspected storm damage until the insurer has had a chance to inspect when practical.
Safety comes before documentation. Do not climb onto a wet, steep, aging, or visibly damaged roof. Photos from the ground can establish the date and visible conditions, while a qualified roofing inspection can document the roof surface, flashing, vents, gutters, and other components safely.
A useful first record includes photos of the property from several angles, roof slopes visible from the ground, downspouts, gutters, screens, skylights, fence damage, outdoor equipment, and any interior stains or active leaks. Photograph hailstones only if it can be done safely, ideally next to an object that shows scale. Save the original files when possible, since they often retain date information.
What a strong hail damage file should include
An insurance carrier needs enough detail to distinguish a recent covered loss from normal aging, installation issues, mechanical damage, or a pre-existing problem. A clear file makes that review easier for everyone involved.
Weather and timeline records
Write down the date and approximate time of the storm, what you observed, and when you first noticed damage or leaking. If neighbors had similar storm effects, that may provide context, but each roof must stand on its own condition and policy coverage.
Keep storm alerts, weather notices, and photographs from the day if available. Do not rely on a general statement that “there was hail in the area.” Tie the event to your address, your roof, and the conditions you observed. If a leak appears days later, document when you discovered it and where water showed up inside the building.
Exterior and interior photos
Photos should be organized, labeled, and broad enough to show location. A close-up of a damaged shingle is useful, but it is stronger when paired with a wider image showing the roof slope or feature where it was found.
For asphalt shingles, an inspector may document impact marks, displaced granules, fractured or creased shingles, exposed mat, and damage to ridge caps. For metal roofs, the record may include dents, damaged seams, fasteners, flashing, coatings, or drainage components. On TPO and other low-slope systems, the evaluation should consider membrane punctures, seam conditions, flashings, ponding areas, drains, and rooftop equipment interfaces.
Interior photos matter when there is water intrusion. Capture ceiling stains, wet insulation, damaged finishes, and the room location. Avoid assuming that every stain came from the recent hailstorm. A proper evaluation should trace the likely path of water and identify whether the issue relates to the roof, flashing, penetration, drainage, plumbing, or condensation.
A written roof inspection report
A roofing report should say more than “hail damage found.” Ask for photo-supported findings that identify the roof type, approximate age if known, number of layers where visible, affected slopes or sections, and related components requiring attention.
The report should also separate storm-related observations from maintenance concerns. For example, a roof can have hail impacts and an unrelated deteriorated pipe boot. Combining everything into one vague damage statement can create confusion. Clear notes help you understand what may be part of a claim and what remains a maintenance responsibility.
Sure Claim Roofing approaches inspections with this distinction in mind: document what is present, explain the condition in plain language, and review the proposed work before you decide. No manufactured damage and no pressure to authorize work before you understand the scope.
Document the whole roof system, not just shingles
Hail claims often focus on the field shingles or visible roof panels, but a roof works as a system. Damage to associated components can affect weather protection and may need to be evaluated with the main roof surface.
| What you are seeing | Documentation to collect | Why it matters | |---|---|---| | Dented gutters, vents, or flashing | Wide and close photos with location notes | Soft metals can show impact evidence even when roof damage is less visible from the ground. | | A new ceiling stain or active leak | Interior photos, date discovered, moisture observations, temporary repair receipts | Establishes the timing, location, and need to prevent further damage. | | Granules in gutters or at downspouts | Photos and roof inspection notes | May support a condition assessment, but granule loss alone does not prove hail damage. | | Flat-roof ponding or drainage concerns | Photos after rain, drain locations, membrane and flashing inspection notes | Low-slope roofs require a system review, especially around seams and drainage paths. | | Aging roof with possible storm impacts | Prior repair records, inspection report, photos of documented impacts | Helps separate existing wear from recent storm-related conditions. |
This broader review is particularly useful for commercial buildings. A warehouse, retail center, or industrial property may have multiple roof sections, rooftop units, restricted access areas, and drainage details that do not appear in a simple residential estimate. Building managers should keep roof plans, maintenance logs, leak reports, tenant notices, and prior repair invoices together. Those records can show whether a problem is new, recurring, or isolated to one area.
Keep invoices, maintenance records, and estimates organized
Save invoices for prior roof repairs, replacements, inspections, cleaning, emergency mitigation, and interior restoration. These documents do not automatically establish coverage, but they can help establish the roof’s history and show that you took reasonable steps to maintain the property.
If you obtain more than one roofing estimate, compare scopes rather than only comparing totals. One proposal may include tear-off, underlayment, flashings, ventilation, code-related items, and disposal, while another may leave several of those items out. A lower number is not always a lower final cost if important work is excluded.
For insurance purposes, a contractor’s scope should be specific about quantities, materials, affected areas, and necessary related work. It should not promise that the insurer will pay for every item. The carrier determines coverage under the policy, while the contractor documents conditions and prices the work required to restore the roof properly.
Be careful with claim language and adjuster meetings
When reporting a loss, describe what you observed without guessing at causes you cannot verify. “I found a new ceiling stain after the April 12 hailstorm” is clearer than “the entire roof is destroyed.” Provide the dates, photos, inspection information, and emergency repair receipts you have collected.
An adjuster inspection is an opportunity to make sure accessible damage and roof components are reviewed. If your contractor attends, their role should be to point out documented conditions, answer construction questions, and explain the written scope. They should not pressure the adjuster or represent that they can control the claim outcome.
If the insurer’s estimate differs from the roofing findings, read both carefully. Differences may involve measurements, material specifications, overlooked components, depreciation, deductibles, policy exclusions, or whether the insurer views an item as storm-related. Ask direct questions and request clarification in writing when needed. A documented supplement request may be appropriate when legitimate, supported work was omitted, but it should be based on facts rather than inflated pricing.
Common documentation mistakes that weaken a claim
The most avoidable mistake is waiting too long after a storm. Delays can make it harder to connect damage to a specific event and allow minor openings to become larger water problems. Review your policy’s reporting requirements and contact the carrier promptly if you believe you have a covered loss.
Another mistake is relying only on distant photos or a contractor’s verbal opinion. Clear, labeled photos and a written inspection report provide a better record. So does documenting all elevations and roof sections, not only the area where a leak appeared.
Finally, do not sign an assignment, authorization, or replacement contract you do not understand. Read the document, ask what you are committing to, confirm who communicates with the insurer, and make sure the scope, payment terms, materials, and warranty responsibilities are written down.
The best time to organize your roof records is before the next storm, but the next best time is while the details are still fresh. Start with what you can document safely, get a clear inspection of the full roof system, and keep every conversation and repair record in one place. That gives you a practical foundation to make informed decisions, whether the next step is a small repair, a claim discussion, or simply monitoring a roof that is still serviceable.